 Managing household finances can be challenging when unexpected expenses, changing income, and rising living costs place pressure on monthly budgets. Although borrowing can sometimes help with temporary financial shortages, repeated reliance on expensive credit may create additional problems. Canadians who have previously considered short-term cash loans online in Alberta may benefit from developing strategies to improve budgeting, increase emergency savings, and reduce the need for future borrowing.
Recognizing Repeated Borrowing Patterns
Occasional financial emergencies can affect households at different income levels.
However, repeatedly using loans to cover rent, groceries, utility bills, or other recurring expenses may indicate an ongoing financial problem.
A borrower might take out a short-term loan to cover an unexpected expense.
When repayment becomes due, less money remains for regular household needs.
This shortage can create pressure to borrow again.
Over time, repeated borrowing fees may make financial circumstances increasingly difficult.
Recognizing this pattern is an important first step toward developing more sustainable financial habits.
Reviewing Household Spending
Understanding where money goes can reveal opportunities to improve financial stability.
Begin by examining several months of bank statements and spending records.
Separate expenses into categories such as housing, food, transportation, insurance, utilities, debt payments, and discretionary purchases.
This process can help identify recurring costs that might be reduced.
Unused subscriptions, unnecessary service upgrades, and frequent convenience purchases may provide possible savings opportunities.
However, a realistic budget should still accommodate essential needs and reasonable personal expenses.
A spending plan that is excessively restrictive may be difficult to maintain.
Establishing Emergency Savings
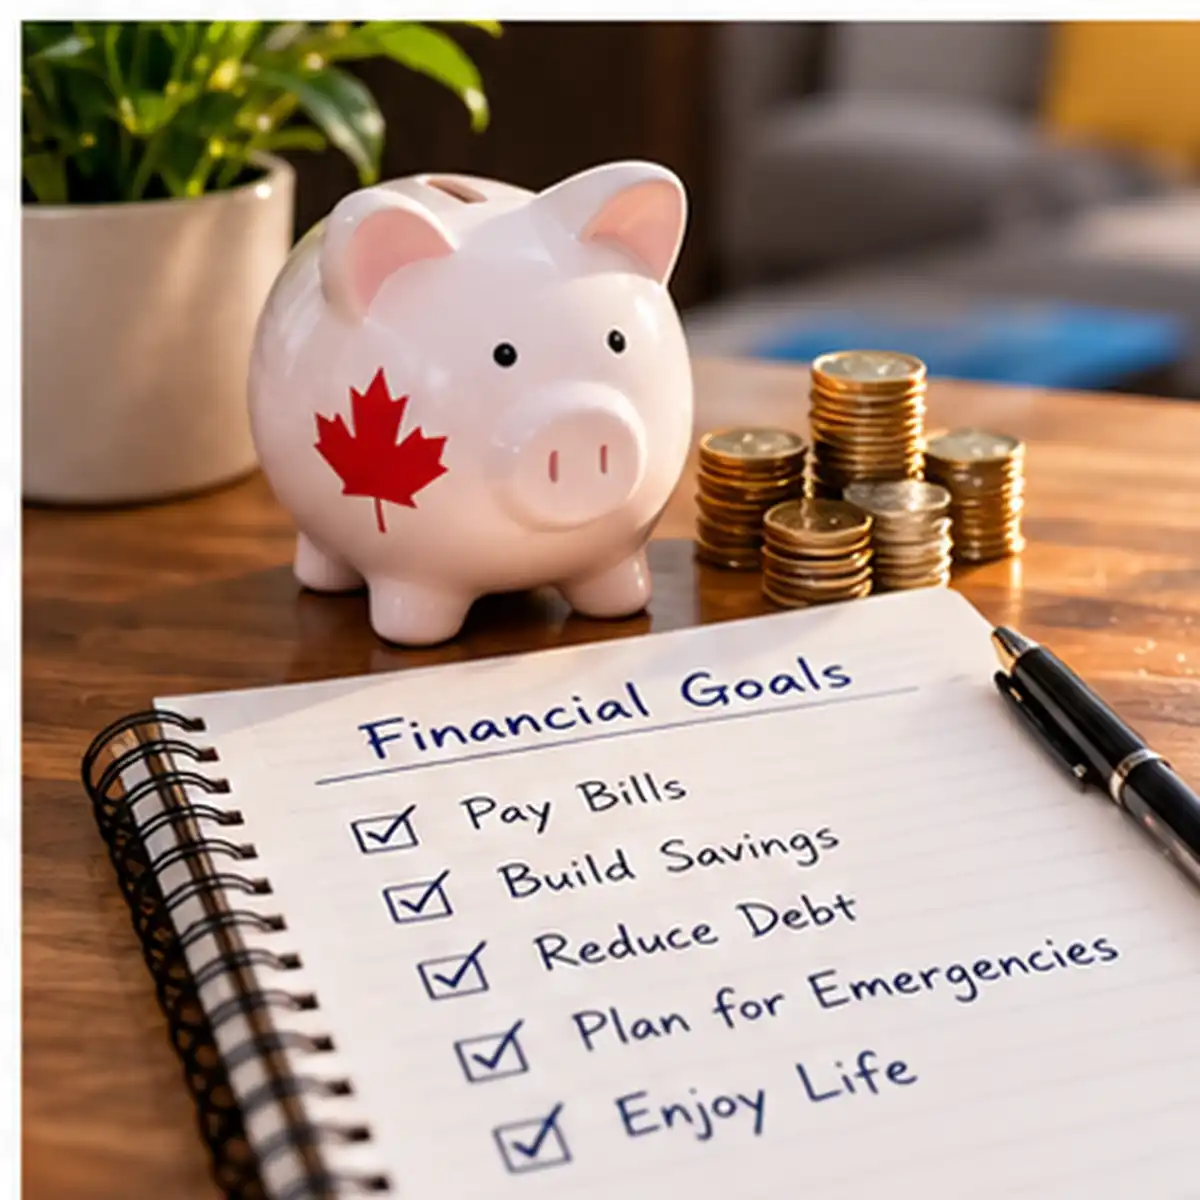
An emergency fund can provide money for unexpected essential expenses.
Although building substantial savings takes time, starting with a modest goal may be more manageable.
Consider saving an initial $100 before gradually increasing the amount.
Even a small reserve can reduce the amount that must be borrowed during an emergency.
Automatic transfers into a separate savings account can help establish consistency.
Contributions should remain affordable after necessary bills and existing financial obligations are covered.
Reducing Expensive Debt
High-interest debt can consume a significant portion of household income.
Review current credit card balances, personal loans, and other borrowing arrangements.
Record interest rates, outstanding balances, and required payment amounts.
This information can help identify which debts are the most expensive.
Some consumers focus additional payments on high-interest balances while maintaining required payments on other accounts.
Others may benefit from professional credit counselling.
Debt consolidation can sometimes be considered, but any proposal should be evaluated carefully to determine whether it actually reduces total borrowing costs.
Communicating With Creditors
When financial difficulties arise, contacting creditors early can sometimes provide additional options.
Utility companies, telecommunications providers, and other businesses may offer payment arrangements or extensions.
Availability depends on the organization and the customer’s circumstances.
Although requests are not always approved, early communication may help prevent additional charges or service interruptions.
It can also reduce the pressure to borrow immediately.
Planning for Irregular Expenses
Some financial problems occur because predictable expenses have not been included in the monthly budget.
Annual insurance premiums, vehicle maintenance, holiday spending, and seasonal household expenses may arrive only occasionally.
Setting aside money throughout the year can make these obligations easier to manage.
For example, an expected annual insurance payment can be divided into smaller monthly savings targets.
Planning for these expenses reduces the likelihood of needing emergency financing.
Exploring Financial Assistance
Canadians experiencing financial hardship may qualify for government benefits, community programs, or other assistance.
Eligibility depends on income, household circumstances, and location.
Nonprofit credit counselling organizations may also provide budgeting support and information about debt management options.
Exploring available assistance can help households identify alternatives to additional borrowing.
Developing Long-Term Financial Stability
Reducing dependence on short-term loans usually requires consistent financial habits rather than one major change.
Tracking spending, building savings, planning for irregular expenses, and managing existing debt can gradually improve financial flexibility.
Progress may be slow, particularly for households with limited income.
However, even modest improvements can make unexpected expenses easier to manage.
The long-term objective is to establish enough financial stability that an unexpected bill does not automatically require another loan application.